×
Blog
The Real Cost of Financing DVC: Why Your Loan Term Matters
By Vacation Club Life /
October 27, 2026
This guest article was provided by Vacation Club Loans, a third-party DVC financing provider. Vacation Club Life is not affiliated with Vacation Club Loans and does not provide financing.
Buying a DVC resale contract through Vacation Club Life can be an incredible way to enjoy years of Disney vacations while saving significantly compared with purchasing direct.
If you’re financing your purchase, however, there’s another number that’s just as important as the purchase price:
How much will your financing actually cost you?
It’s easy to focus on finding the lowest monthly payment. But when comparing DVC financing options, buyers should look beyond the payment and consider the interest rate, loan term, fees and total amount paid over the life of the loan to really maximize your resale savings.
A Lower Monthly Payment Isn’t Always the Least Expensive Option
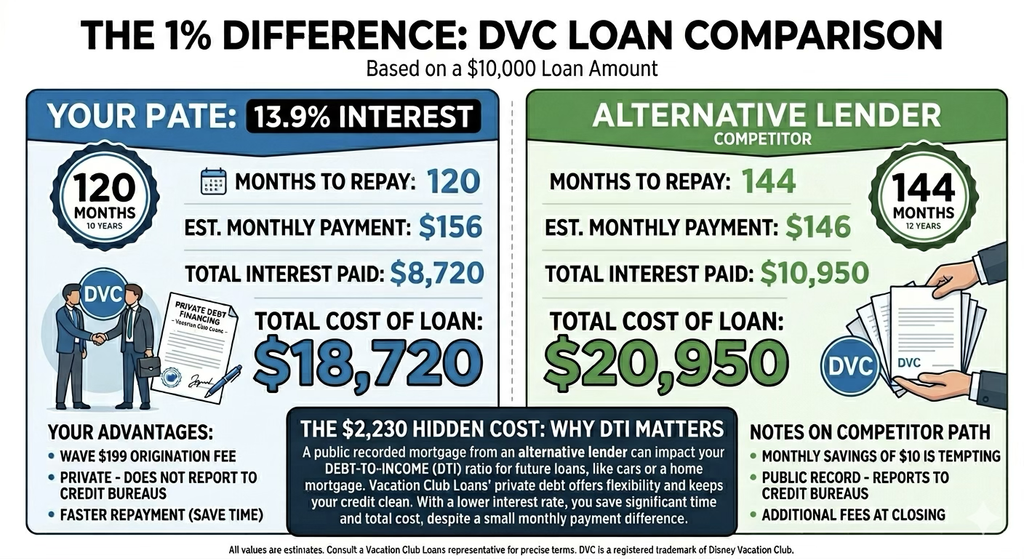
Extending a loan over additional years will usually lower your monthly payment. That’s appealing, but those extra years can also mean paying considerably more interest.
For example, a buyer considering a longer 12-year loan may see a $20 per month in a lower monthly payment than a 10-year loan and assume it’s the better deal.
But ask one more question:
How much will I have paid when the loan is completely paid off?
Those additional two years of interest can add thousands of dollars to the total cost of a DVC purchase, especially when the longer loan also carries a higher interest rate.
At Vacation Club Loans, we generally recommend a 10-year maximum term for larger DVC loans because it offers a balance between keeping the monthly payment manageable and avoiding unnecessary years of interest. Vacation Club Loans does not charge a higher interest rate of the maximum term of 10 years too! With us, your rate is credit worthiness-driven so you can take advantage of lower payments without losing on savings.
And remember: you don’t have to keep the loan for 10 years just because the term starts this way. We often recommend starting with the 10 year obligation which is very affordable but making a few additional principal only payments along the way and taking advantage of our NO PREPAYMENT PENALTY offer!
Pay It Off Early, Without a Penalty!
Vacation Club Loans charges $0 in prepayment penalties.
That means you can choose a comfortable monthly payment today and still pay additional principal or pay the loan off completely whenever your budget allows.
Tax refund? Bonus at work? Extra money one month? Put it towards the principal using our “state of the art” online portal. The faster you reduce your principal balance, the less interest you pay over time.
Don’t Forget About Fees
Interest isn’t the only cost buyers should compare.
Some lenders charge a loan origination fee simply for originating the financing.
Vacation Club Loans charges a $0 loan origination fee.
That means more of your money stays with you instead of being spent on a lender fee at closing.
There will still be normal mortgage-related recording fees and taxes associated with financing a DVC purchase, but those are different from a fee charged to you without you getting any benefit.
Compare APR: Not Just the Advertised “Starting At” Rate
You’ve probably seen lenders advertise rates that “start as low as” a certain percentage.
That’s useful information, but it doesn’t necessarily tell you what your loan will cost.
The rate you actually qualify for can depend on your credit, down payment, loan term and the financing program you choose. Vacation Club Loans does not charge a higher interest rate of the maximum term of 10 years too!
That’s the number that matters.
Four Numbers to Compare Before You Finance
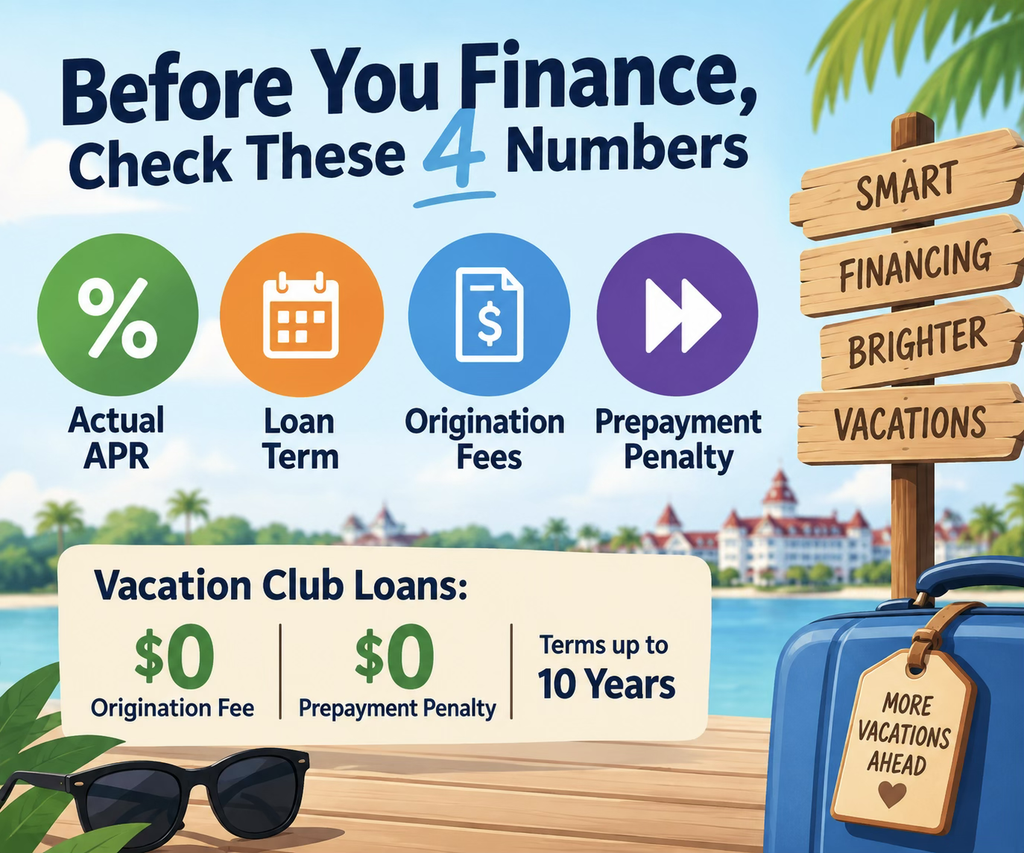
Before selecting your DVC financing, compare:
1. Your actual APR
Not just the lender’s advertised starting rate.
2. Your loan term
A lower payment stretched over additional years may cost substantially more.
3. Your lender fees
Vacation Club Loans charges a $0 loan origination fee.
4. Your prepayment options
Vacation Club Loans has no prepayment penalty, so you’re free to pay your loan off early and reduce the interest you pay.
Keep the Savings in DVC Resale
One of the biggest reasons buyers choose Vacation Club Life is DVCs resale value.
Financing can be a wonderful tool that allows you to purchase the DVC contract TODAY that’s right for your family without paying the entire purchase price upfront. Now is a great time to buy with low price per points in the market.
But financing should complement the savings you found buying resale — not quietly eat away at those savings through unnecessary fees or years of additional interest.
Take a few minutes to compare the total numbers before you finance.
Your monthly payment matters.
But what you ultimately pay matters even more.
About Vacation Club Loans
Vacation Club Loans specializes in financing Disney Vacation Club resale purchases and has been helping buyers finance their vacation ownership since 2016.
We offer flexible financing options, competitive fixed rates, $0 loan origination fees and $0 prepayment penalties. Our Loan Calculator is a great way to plan out your future monthly payments. For our buyers who wish to keep their credit worthiness confidential, we also offer a No Credit Check option.
For information or a personalized financing quote, visit www.VacationClubLoans.com

Posted By: